Agricultural finance
Payments that follow the farming year.
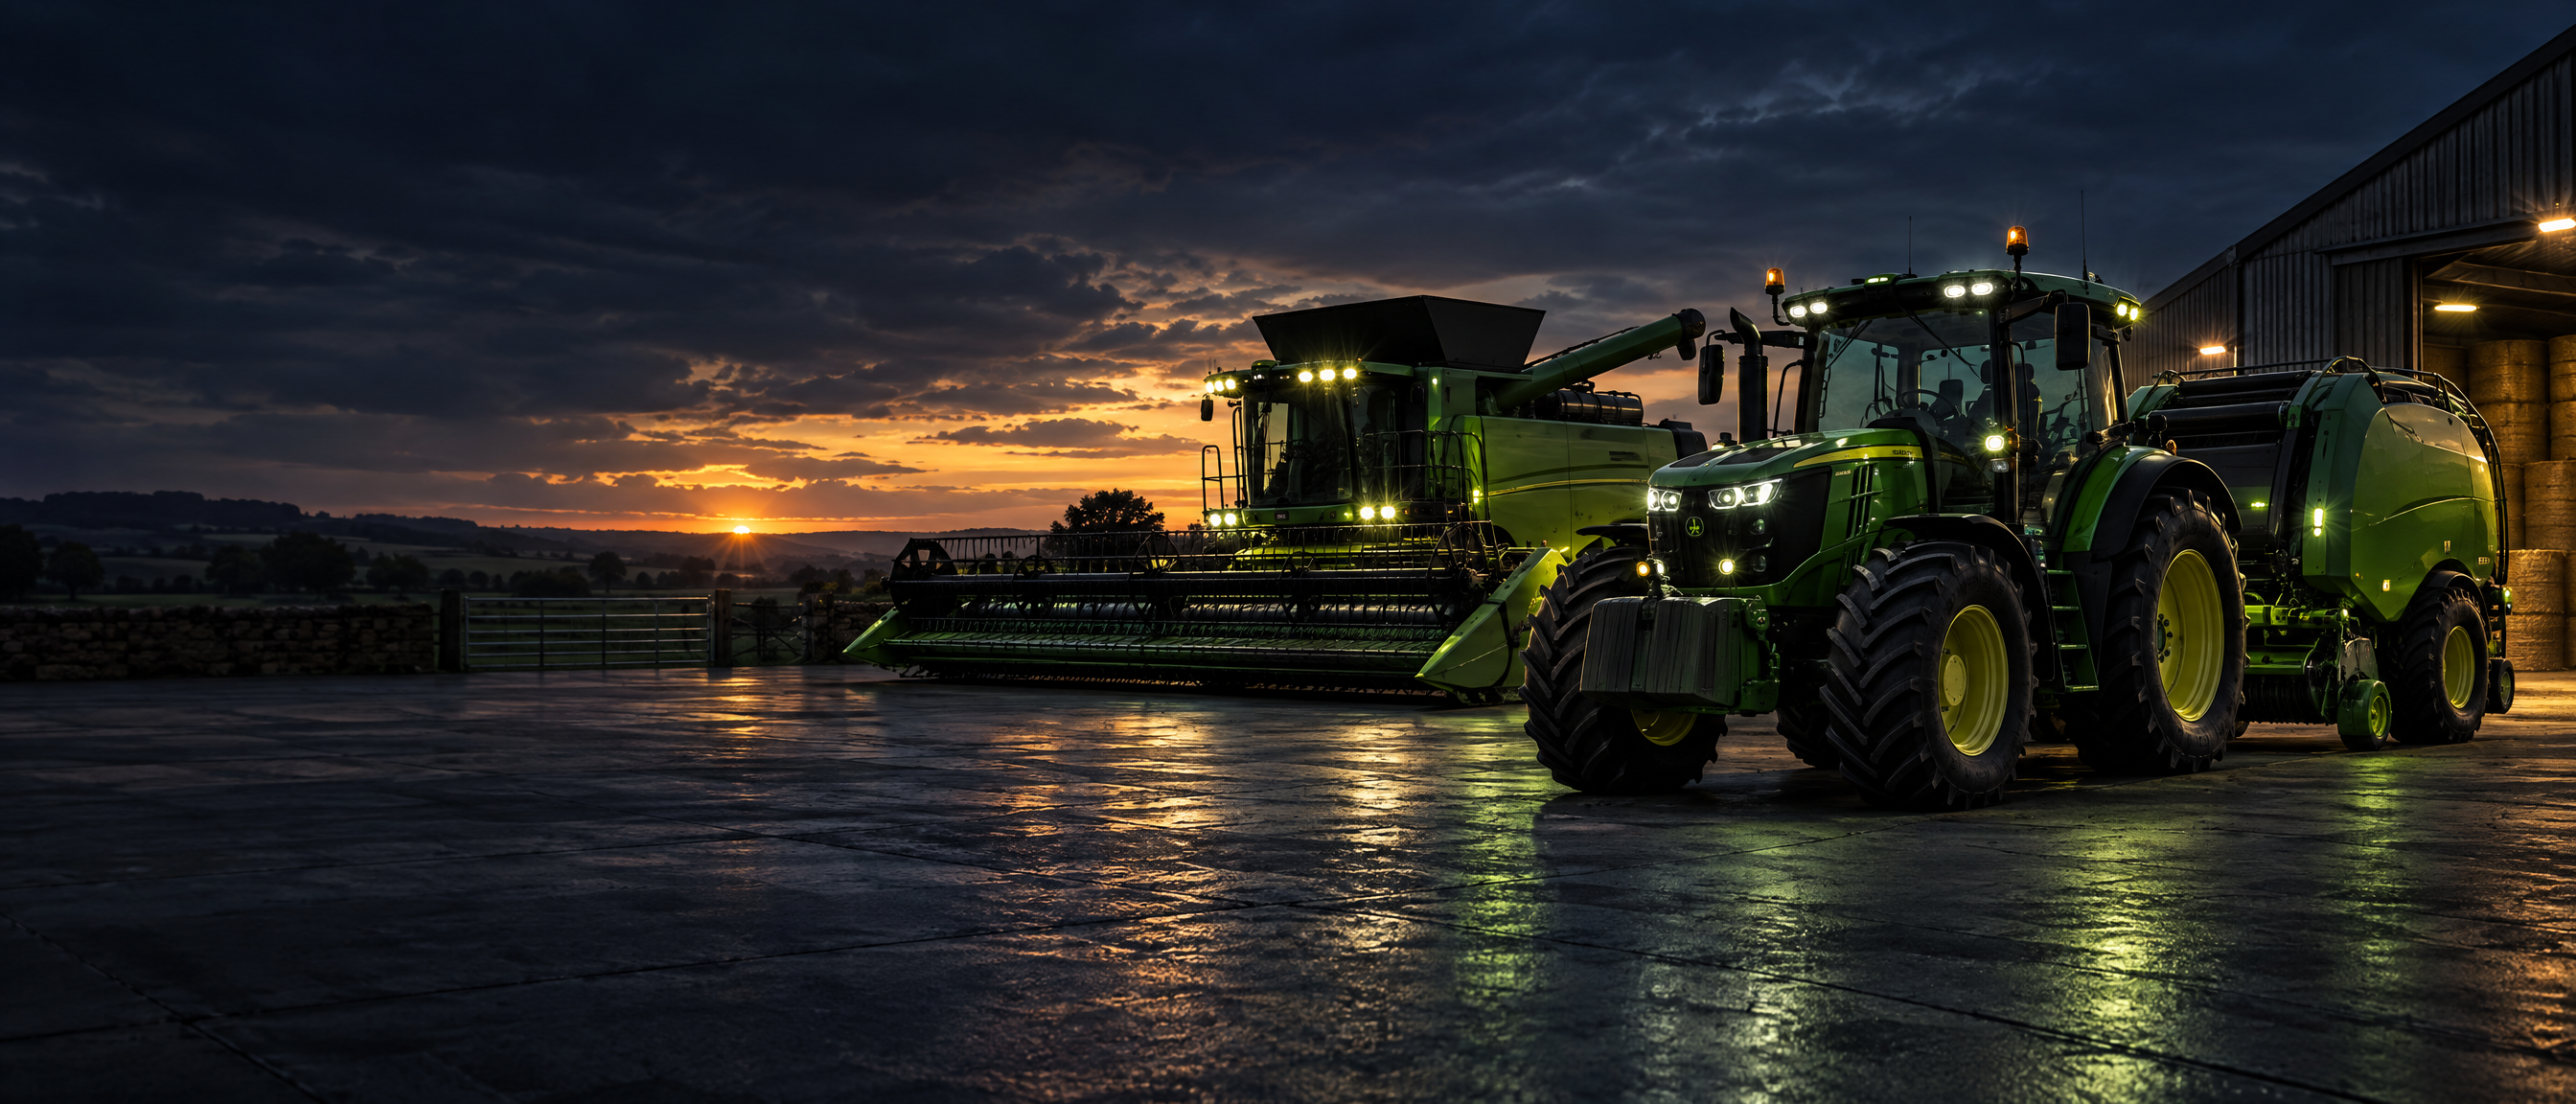
Tractors, harvesters and implements funded with structures that can reflect seasonal income.
A more useful starting point
Agricultural finance: what matters before you enquire
Agricultural finance needs to reflect the farming year. A tractor, combine, sprayer or storage project may be productive for years, but income can arrive in seasonal peaks rather than evenly each month.
Who commonly uses it: Farms, agricultural contractors, growers, livestock businesses and rural enterprises use finance for replacement, capacity, compliance, storage and efficiency projects.
Routes to compare: Hire purchase can suit long-life machinery the business intends to own. Finance lease can spread rentals and support replacement cycles. Refinance can release value from owned machinery to fund inputs, land work or expansion.
What we can fund
Common funding routes
Match the structure to the job the asset must do.
There is no universal best route. Compare ownership, useful life, deposit, payment profile, VAT, security and the end-of-term plan.
Hire purchase →
Hire purchase splits the price of an asset into regular payments. Once the final instalment and any option fee are paid, ownership passes to your business.
Finance lease →
With a finance lease you rent an asset for most of its useful life. The lender keeps legal ownership while your business enjoys full use of the equipment.
Asset refinance →
Refinancing raises funds against assets your business already owns or is still paying for, releasing equity while the equipment keeps working.
Broker tips
- ●Seasonal or annual payment profiles may be possible
- ●Have dealer quotes and farm accounts ready
- ●Refinancing owned machinery can fund inputs or expansion
Prepare a credible brief
Information that keeps the conversation moving.
- ✓Dealer quote, specification, hours, registration/serial number and delivery timing
- ✓Latest accounts, management figures or tax returns where requested
- ✓Farm plan, contract work, harvest timing or other explanation of seasonal income
- ✓Existing machinery finance, land/lease context and any grant or subsidy timing relevant to the purchase
Plan the economics
Questions lenders and owners will care about.
- →Seasonal, quarterly or annual payment profiles may be more useful than equal monthly payments
- →Consider downtime, servicing and whether the new machine replaces or complements existing capacity
- →Harvesters and specialist implements may have narrow delivery and resale windows
- →Energy, storage and efficiency projects need a credible savings or yield estimate
Typical use cases
What this can look like in practice.
Can payments match harvest income?+
Some lenders offer seasonal profiles with larger payments at peak months.
Can repayments match the farming year?+
Some lenders offer seasonal profiles, but they need evidence of the income pattern.
Can implements be financed separately?+
Often, provided the asset has a clear value and supplier trail.
Will a grant affect the finance?+
Explain the timing and conditions early so the proposal reflects the real cash flow.
Next step
Start your quote
Tell us about the agricultural finance you are considering. Choose phone, WhatsApp or email as your preferred contact. No credit search to enquire.
Ready to fund your next asset?
Two minutes to share the details. No credit search from this website. A broker replies during opening hours.